PB Comms wins Agency of the year at the 2026 MAX awards
Now Available:
PB Comms wins Agency of the year at the 2026 MAX awards
At this year's MAX Awards, PB Comms won Agency of the year, a category voted by the Financial Standard editorial team. The award recognises agencies specialising in media, public relations or creative services that have driven strong growth and measurable results for their financial services clients. A big congratulations to the whole PB Comms team for always going above and beyond.
Robeco has published the 16th edition of its 5-year outlook, Expected Returns 2027-2031, this year titled The Great Rewiring. The outlook explains that just like human brains which rewire themselves when faced with disruption, the global economy is building new pathways, rewiring trade, capital and production.
The outlook says the desire for greater energy security and the rise of artificial intelligence, which is remodeling the entire business landscape, means the age of efficiency is gradually giving way to an age of plasticity. For much of the past three decades, investors operated in a world optimized for efficiency. Today, economic architecture is moving from a ‘just-in-time’ efficiency to a ‘just-in-case’ resilience.
Geopolitical fragmentation such as the closure in 2026 of the Strait of Hormuz, through which one-sixth of the world’s energy supplies pass, exemplifies this well. The global economy is creating new ways of circumventing these chokepoints, not least in a surge of investment in renewable energy sources to reduce reliance on fossil fuels.
A new kind of Renaissance
Peter van der Welle, Strategist Multi-Asset Solutions at Robeco: “Last year we argued that the world was entering a ‘Stale Renaissance’: a period in which extraordinary technological progress coexisted with a drag from elevated economic policy uncertainty. This year we remain firmly committed to the Renaissance part of that thesis, but are now inclined to nuance the ‘stale’ element.”
Laurens Swinkels, Head of Solutions Research at Robeco: “What has changed is our understanding of the cyclical implications of the capex underway to facilitate the AI revolution, as well as the resilience of the global economy in light of the huge supply disruption to the global oil market due to the closure of the Strait of Hormuz, plus the aftermath of the highest US tariffs since the 1930s. This resilience stems from the ability to adapt and rewire in spite of emerging chokepoints.”
The three dimensions of the Great Rewiring
The ‘Great Rewiring’ is seen occurs along three closely related dimensions that will have ramifications for future asset returns. First, trade is being rewired as firms diversify supply chains and governments increasingly value security alongside efficiency. The world is not deglobalizing, but instead it is reorganizing, creating more dispersion in cross-regional trade volumes.
Second, the role of capital is being rewired, as we have arrived at a major inflection point from a consumption-led economy toward a more investment-led one. The physical economy led by massive AI and renewable energy infrastructure is on the rise; the asset-light economic model may start to lose ground in the next five years.
Third, production itself is being rewired. The next phase of the AI-led productivity renaissance will be led by firms that manage to transform and redesign production processes around it. We believe that AI will predominantly augment labor instead of displacing it.
Base, bull and bear cases
Expected Returns offers a base, bull and bear case in how this may play out over the next five years:
Base case: The ‘Great Rewiring’ (50% probability)
The Great Rewiring causes a rejuvenated expansion. This is ultimately a story of a successful value transfer from AI enablers to AI adopters. Yet, it comes at a cost of higher inflation and technological unemployment. The rewiring of trade encourages resilience rather than efficiency, the rewiring of capital raises investment intensity, and the rewiring of production lifts productivity through automation.
Bull case: The ‘Luminous Renaissance’ (15% probability)
The Great Rewiring proves substantially more successful than anticipated in raising trend GDP growth and delivering benign disinflation. This scenario sees the global economy experience a genuine productivity renaissance reminiscent of the late 1990s. The key difference is that AI proves more transformative because it accelerates not only automation but also its own diffusion.
Bear case: The ‘Synaptic Decay’ (35% probability)
The Great Rewiring stalls before its benefits can be realized. The economy continues to incur the costs of adaptation while failing to capture the expected gains from AI. What begins as a deflationary overcapacity story as the AI bubble implodes gradually morphs into more troubling stagflation. Inflation remains structurally elevated and the global economy loses connectivity faster than it gains adaptability.
Investment implications
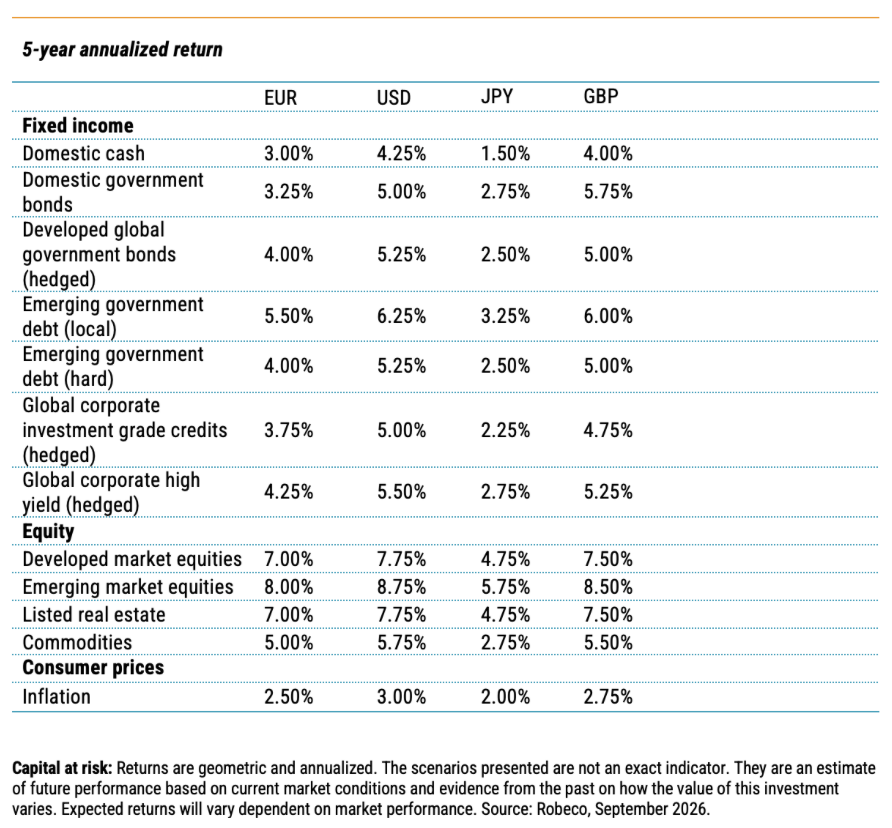
For asset class returns, this ‘Great Rewiring’ means that equities are again the most favored, followed by real estate. We expect emerging market equities to deliver the highest five-year annualized returns of 8.0% in euros, followed by developed market stocks returning 7.0%. Listed real estate is also seen delivering 7.0%, with the most positive outlook for Real Estate Investment Trusts (REITs) since 2014.
Expected Returns forecasts for the major asset classes (base case)
In fixed income, the highest five-year annualized returns are seen at 5.5% coming from emerging market debt (EMD) denominated in local currency. EMD in hard currency is seen returning 4.00%. Developed global government bonds (hedged) are also seen delivering 4.0%, while domestic government bonds are forecast to return 3.25%. In credits, global corporate high yield bonds (hedged) are forecast to return 4.25%, while their investment grade counterparts are seen delivering 3.75%.
Commodities, whose returns are heavily influenced by conflicts and the value of the US dollar, are expected to return 4.0%. Domestic cash is forecast to return 3.0%, putting it slightly above the predicted inflation rate of 2.5%, which is seen remaining at 3.0%, and will have implications for interest rate policy over the coming period.
Special topics
This year’s report also features four special topics that reflect the evolving investment landscape:
‘Chokepoints and energy security 2.0: How the Middle East conflict has redefined reliably securing power supplies in favor of renewables.
Emerging markets: A world of different destinies: Exploring the diversity of differing countries, from the tech-heavy to the resource rich.
Private credit: Opportunity, risk and selectivity in a maturing market: What was once a more specialized source of financing, has become a multi-trillion-dollar asset class.
Beyond sustainability: Generalized 3D investing: Adding the third dimension of sustainable investing to modern portfolio construction